

By Ross Morrison, partner, primary investments at Adams Street Partners, London
The European and UK venture ecosystem hit the ground running in 2026, minting nine new unicorns in the first quarter alone[1]. The UK also recorded the largest acquisition of a UK artificial intelligence (AI) start-up with Accenture’s purchase of one of the leading application companies, Faculty, at over £1bn[2], and saw the successful financing of London-based AI voice platform ElevenLabs at $11bn[3].
We believe long-term structural growth and firm foundations of world-class talent and mature capital markets underpin this momentum. European venture capital investment levels tripled over the past decade, helping the continent to produce 25% of new global venture backed unicorns in 2025, a clear marker of the strength of the region’s talent[4]. This growth has translated into increased liquidity for limited partners—exit value came in at €67.8bn in 2025, the second-highest annual total on record[5].
Europe is therefore a sizeable and established market for innovative companies that can become the next wave of global category leaders.
UK investors with a mandate to allocate to British assets should note that the country is Europe’s largest venture market. Over the past decade, about a third of European venture deal value has been in the UK, according to PitchBook[6]. The UK is also Europe’s leading unicorn engine, with 176 private companies valued above $1bn, versus 73 in Germany and 48 in France[7].
Accelerating flywheel
This data points to a venture ecosystem with durable momentum. Dealroom data show the combined enterprise value of European venture-backed technology companies rising almost 24-fold since 2010 to nearly $4tn[8] (Figure 1). This highlights Europe’s ability to compound value over multiple cycles, making the European venture-backed ecosystem comparable in scale to some major European public market indices.
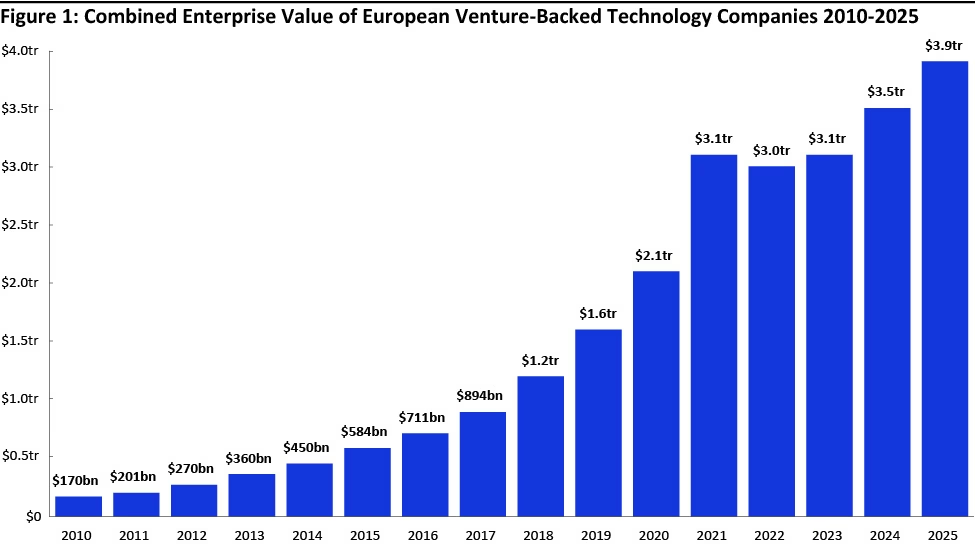
Source: Dealroom
Yet many institutional venture portfolios remain underweight Europe relative to its footprint, which can leave investors underexposed to the region’s category leaders and overconcentrated in other markets. A measured rebalancing towards Europe and the UK can improve diversification, increasing the chances of capturing upside from some of the world-class innovation taking place on the continent.
There are signs that institutional investors are increasingly recognizing the opportunity that the European market presents. In Adams Street’s 2026 global investor survey, respondents ranked Europe as the most attractive market for private markets investment opportunities this year.
Talent driven founder engine
A key driver of Europe’s venture edge is its talent pool. Europe has long been known for the strength of its technical talent, with four of the current top 10 universities for computer science being located there[9].
Over the past decade, Europe has been relatively effective in converting this talent into repeat entrepreneurship. Many well-known scale-ups now operate as ‘founder factories’ that spawn the next generation of start-ups. Alumni from European champions have gone on to found scores of new companies, including to name just a few: Klarna (66), Spotify (61), Zalando (56), Criteo (54), Deliveroo (53), Revolut (46), and Delivery Hero (43)[10]. This is a strong signal of ecosystem maturity, as successful companies are now producing the next cohort of repeat founders.
Fragmentation: a feature, not a bug
Breakout companies are being founded across the continent – UiPath (Romania), Spotify (Sweden), Celonis (Germany), Revolut (UK), and Veriff (Estonia), for example. To date, more than 600 unicorns have come from 66 different European cities. [11]
Fragmentation is reflected in the venture manager base. The number of active funds has expanded markedly over time (Figure 2), reflecting both ecosystem growth and the breadth of firms competing for the best opportunities. For UK institutional investors, the implication is that capturing the full European opportunity set typically requires a portfolio built across leading, established franchises and locally embedded next-generation managers. In an access-constrained market, manager selection is a core return driver. Adams Street has a 25-year track record investing in European venture, dating back to its first European venture capital fund investment in 2000.
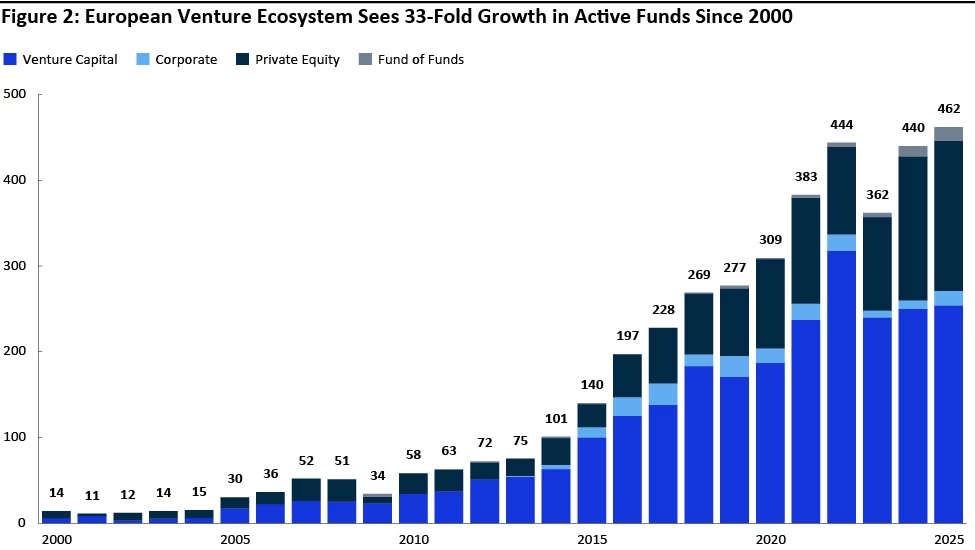
Source: Dealroom
AI application edge
Europe’s advantages are once again coming to the fore in the age of AI. Its deep technical talent base – trained in top universities and pioneering AI labs such as DeepMind – drives its strength in AI.
European companies, such as UK-based Synthesia and ElevenLabs, have emerged as category leaders. Accel data shows that, (ex-large language models), venture investment into AI and cloud in Europe, the Middle East and Africa ran at roughly half to two-thirds of US levels from 2022 to 2025 (estimate)[12], which is a leading positive forward indicator of company creation and successful outcomes.
From thesis to action
Europe offers UK institutional investors a significant opportunity to potentially access the next generation of venture-backed multibillion-dollar outcomes, especially as AI reshapes competitive advantage across industries. It also provides the same investors an outsized ability to double down on UK founders, companies and innovation.
In our view, the most effective path is a diversified manager portfolio, combining leading established firms with high-quality emerging specialists embedded in local ecosystems, and supported by disciplined selection and consistent access.
Adams Street Partners, LLC, is a leading private markets investment management firm with more than $65bn in assets under management.
[1] Aikido, Allica Bank, Advanced Machine Intelligence Labs, Cast AI, Entrepreneur First, Harmattan AI, Olix, Osapiens, and Preply.
[2] Source: Financial Times.
[4] Source: Dealroom.co, as of November 18, 2025. Europe includes Israel.
[5] Source: PitchBook 2025 Annual European Venture Report.
[6] Source: PitchBook Q3 2025 European Venture Report.
[7] Source: Dealroom.co, as of November 06, 2025.
[8] Source: Dealroom.co. from companies founded or with HQ in Europe
[9] Source: Times Higher Education Rankings.
[10] Source: Dealroom.co. Data as of March 31, 2025.
[11] Source: Dealroom.co and LocalGlobe. Data as of May 23, 2025.
[12] Source: Accel 2025 Globalscape.
This communication (the “Communication”) is provided for educational purposes only and is not investment advice or an offer or sale of any security or investment product or investment advice. Offerings are made only pursuant to a private offering memorandum containing important information. Statements in this Communication are made as of the date of this Communication unless stated otherwise, and there is no implication that the information contained herein is correct as of any time subsequent to such date. All information has been obtained from sources believed to be reliable and current, but accuracy cannot be guaranteed. References herein to specific sectors, general partners, companies, or investments are not to be considered a recommendation or solicitation for any such sector, general partner, company, or investment. This Communication is not intended to be relied upon as investment advice as the investment situation of individuals is highly dependent on circumstances, which necessarily differ and are subject to change. The contents herein are not to be construed as legal, business, or tax advice, and individuals should consult their own attorney, business advisor, and tax advisor as to legal, business, and tax advice. Past performance is not a guarantee of future results and there can be no guarantee against a loss, including a complete loss, of capital. Certain information contained herein constitutes “forward-looking statements” that may be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “estimate,” “intend,” “continue,” or “believe” or the negatives thereof or other variations thereon or comparable terminology. Any forward-looking statements included herein are based on Adams Street’s current opinions, assumptions, expectations, beliefs, intentions, estimates or strategies regarding future events, are subject to risks and uncertainties, are provided for informational purposes only and do not constitute a guarantee, promise, projection, forecast or prediction of, or representation as to, the future. Actual and future results and trends could differ materially, positively or negatively, from those described or contemplated in such forward-looking statements. Moreover, actual events are difficult to project and often depend upon factors that are beyond the control of Adams Street. Adams Street neither (i) assumes responsibility for the accuracy or completeness of any forward-looking statements, nor (ii) undertakes any obligation to update or revise any forward-looking statements for any reason after the date hereof. Also, general economic factors, which are not predictable, can have a material impact on the reliability of projections or forward-looking statements. Adams Street Partners, LLC is a US investment adviser governed by applicable US laws, which differ from laws in other jurisdictions.