

Stuart Dunbar, partner at Baillie Gifford, argues that as a growing share of assets moves into low-cost passive funds, companies backed by a select group of active investors can deliver outperformance.
The debate on the value – or otherwise – of active management has existed since Jack Bogle of Vanguard first invented the passive fund in the 1970s. Incumbents with vested interests on both sides make their own self-serving arguments, each showing empirical evidence that proves their point. The real lesson is that vested interests cloud objectivity, and selective use of statistics is an advanced form of art.
It is therefore with self-awareness that we once again make the argument for active management, and that it is in fact becoming more important to achieving good outcomes for investors. Readers should rightly be cynical. But our arguments are at least not those we have heard ad nauseum before.
The past few years have seen attempts by regulators and governments to guide capital to where it has the greatest impact on real-world productivity. This is uncontroversial in principle, but in practice has resulted in equating productive capital deployment entirely to private markets. Private markets have a huge role to play, but this narrow interpretation of how our overall financial system works is likely to have unintended negative consequences.
Capital is not in practice deployed by financial market participants. It is deployed by the management of the companies in which we invest. They decide every day how much to spend on capital, training, R&D, marketing and any number of other things. These decisions are what make a business successful or otherwise. Productive investment does not depend on whether a company is public or private, or whether it is funded by primary capital or cashflow; it depends on the ambitions, horizons, capability and choices of management. The role of shareholders – that is, true investors, not speculators – is to identify companies with future potential and then assess, create and enable the conditions in which management can confidently take the decisions that create real long term value.
Such true investors are sometimes known as ‘quality shareholders’ , defined as investors who select a small number of companies and invest meaningfully, hold their stakes for considerable periods of time, and who are available to engage with managers and boards for consultation if needed.
As assets move into low cost quantitative and passive investment approaches, and average holding periods reduce to months not years, the influence of quality shareholders in public markets is waning. The deep levels of company-specific knowledge necessary to act as an engaged owner are not attainable within the economic realities of low-cost very diversified investment approaches. Thus the supportive conditions for long term wealth creation are becoming less common, so much so that stock markets are in some places no longer deemed ‘productive’ at all. If correct this kicks away one of the very foundations of our investment system. The good news is it’s not as simple as that. We need to switch attention from the artificial public-private divide and instead focus on shareholder–management relationships more generally.
The amount of cashflow available for growth within listed companies dwarves that of private markets, and its effective deployment is central to real-world wealth creation at scale. Engaged active management by quality shareholders within listed companies matters. Studies show clear correlations: the more ‘ownerless’ a company is, the higher the likelihood of earnings manipulation, misalignment of managerial rewards, accounting misconduct and financial fraud.[SD1]
Markets do not exist in a vacuum. Companies respond to the actions or inactions of shareholders, and the regulatory environment in which they operate. Ambitious growth companies – the very ones that matter most for socially beneficial productivity gains – do not want to be beholden to disengaged short-term shareholders who at best care about quarterly earnings. This is driving more companies to stay private or even delist.
The following graphic is from a study undertaken by a NY-based think tank, FCLT. It sets out how different companies self-identify in terms of appetite for innovation, risk and shareholder engagement.
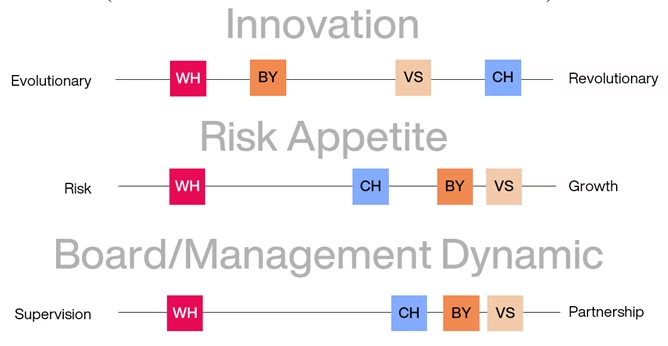

Widely held public companies – those that lack engaged shareholders – show low appetite for innovation, risk and shareholder engagement. In sharp contrast, closely held public companies – those with a small number of large shareholders who build relationships with management and typically own shares for very long periods (ie. quality shareholders) – have much higher appetites for innovation and risk, and have stronger shareholder relationships.
This distinction matters not just for economic productivity but for investment returns. Academic studies show that public companies where management and shareholders have constructive, engaged relationships and long-term alignment outperform those that don’t. The lack of attention to this in public markets is leading to increasing dysfunction.
Where does this end? I believe there are a number of likely unintended consequences. As quality shareholders diminish as a proportion of investors, the effectiveness of the financial system in supporting effective capital deployment within listed companies reduces. The effect is virtually impossible to isolate, but is almost certainly significantly negative for society-wide productivity gains and listed company returns. Passive investors will track the index, but index returns will be lower. Not everyone can be a free-rider.
The fees associated with accessing private companies are much higher even than active stock selection and high engagement approaches to investing in public companies. As growth concentrates in private markets, the cost of investment return per unit may well, counter-intuitively, go up rather than down.
None of this is to suggest that private markets do not play a crucial role in facilitating the funding of innovation and growth. They clearly do. Rather, it is a plea to understand the consequences of letting the public equity system fail. Equity market returns don’t just happen in a vacuum. They are the product of a system of investor oversight and engagement that must be adequately resourced. Ignoring this will cost us all in the end.